Institutional FX Insights: Credit Agricole FX Weekly 25/9/26
G10 FX & CROSS-ASSET STRATEGY BRIEFING: USD RALLY RESUMPTION
Desk Analysis: Macro Rates, FX Options & Seasonal Flows
THE TAKE: FRONT-END US RATES DRIVING G10 REALIGNMENT
The US Dollar (USD) rally has re-accelerated in lockstep with a sharp, global expansion in Developed Market (DM) yields. Short-dated US rates are leading the move, with the 2-Year SOFR rate logging its largest monthly surge in years (>50 bps) to hit new multi-year highs.
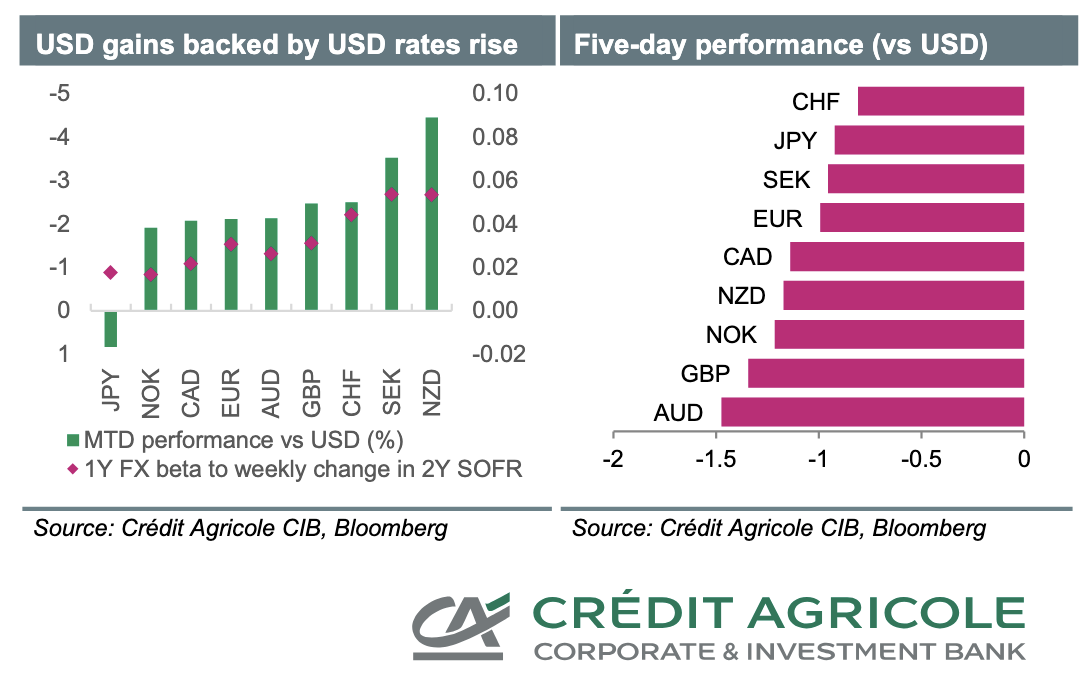
A 1-year regression on weekly G10 currency returns shows that 2Y US rates explain the vast majority of month-to-date FX performance via relative rate sensitivity (beta):
Laggards (High Sensitivity / Weak Drag): NZD has significantly underperformed relative to its rate regression beta.
Outperformers (Intervention Backstop): JPY has held up better than implied by rate differentials alone, as active threats of official FX intervention from Japanese authorities act as a floor.
OCTOBER SEASONALS & OPTION MARKET SHIFTS
October Seasonal Tailwinds: Historical flow patterns suggest the USD rally has further room to run. On average since 2000, the USD Nominal Effective Exchange Rate (NEER) experiences its largest monthly gains during October. In US midterm election years, the USD NEER has logged only a single negative October return over that 25+ year period.
Equity Outperformance & Month-End Rebalancing: USD gains have coincided with relative outperformance in US equities, driven by heavyweights. Month-end portfolio rebalancing flows are expected to remain light, limiting immediate downside flow drag on the greenback.
Options Surface Dynamics (USD Calls & EUR Vulnerability):
Spot strength has spilled over into the derivatives space, with implied volatilities rising alongside spot gains and USD calls richening.
In short-dated tenors (1-Month), this hawkish vol shift has been most pronounced against EUR, highlighting EUR/USD as the most vulnerable G10 pair into October.
GLOBAL MONEY MARKETS & CENTRAL BANK DIVERGENCE
European Rates (ECB): Short EUR rates have tracked US yield increases most closely. However, with the ECB already anticipating a Q426 inflation peak above 3.5%, the upcoming September Eurozone CPI print faces a high bar to alter market pricing.
Japanese Rates (BoJ): Short JPY money market rates continue to lag the global rise, leaving the Yen reliant on verbal and physical intervention rather than rate support.
Australian Rates (RBA): An RBA rate hike is almost fully priced for next week, with 1–2 additional hikes already discounted by Q127. Despite AUD offering the highest yield in G10, high rate expectations are already fully priced, limiting fresh upside emboldening for the currency.
SUMMARY G10 CROSS-CURRENCY TACTICAL MATRIX
US Dollar Index (DXY / NEER): Strong Bullish Bias — Supported by 2Y SOFR expansion (>50 bps MoM) and favorable October seasonal patterns.
EUR/USD: Bearish Target / Top Short Focus — Short-dated (1M) USD call skew is steepest vs. EUR; ECB rate response is already exhausted.
USD/JPY: Tactical Range / Intervention Capped — Rate differentials argue for upside, but intervention threats limit breakout speed.
NZD/USD: Underperformance Drag — Lagging furthest behind its rate beta regression models.
AUD/USD: Neutral / Fully Priced — RBA rate hikes fully discounted; high carry insufficient to overcome broader USD momentum.
Disclaimer: The material provided is for information purposes only and should not be considered as investment advice. The views, information, or opinions expressed in the text belong solely to the author, and not to the author’s employer, organization, committee or other group or individual or company.
Past performance is not indicative of future results.
High Risk Warning: CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 69% and 73% of retail investor accounts lose money when trading CFDs with Tickmill UK Ltd and Tickmill Europe Ltd respectively. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
Futures and Options: Trading futures and options on margin carries a high degree of risk and may result in losses exceeding your initial investment. These products are not suitable for all investors. Ensure you fully understand the risks and take appropriate care to manage your risk.
Patrick has been involved in the financial markets for well over a decade as a self-educated professional trader and money manager. Flitting between the roles of market commentator, analyst and mentor, Patrick has improved the technical skills and psychological stance of literally hundreds of traders – coaching them to become savvy market operators!